What to do after a commercial fire on Van Nuys Boulevard
A commercial fire on Van Nuys Boulevard in Pacoima leaves you with two urgent jobs: secure the property and start the insurance claim. Here is the exact order of steps we walk business owners through, from the first hour to reopening day.
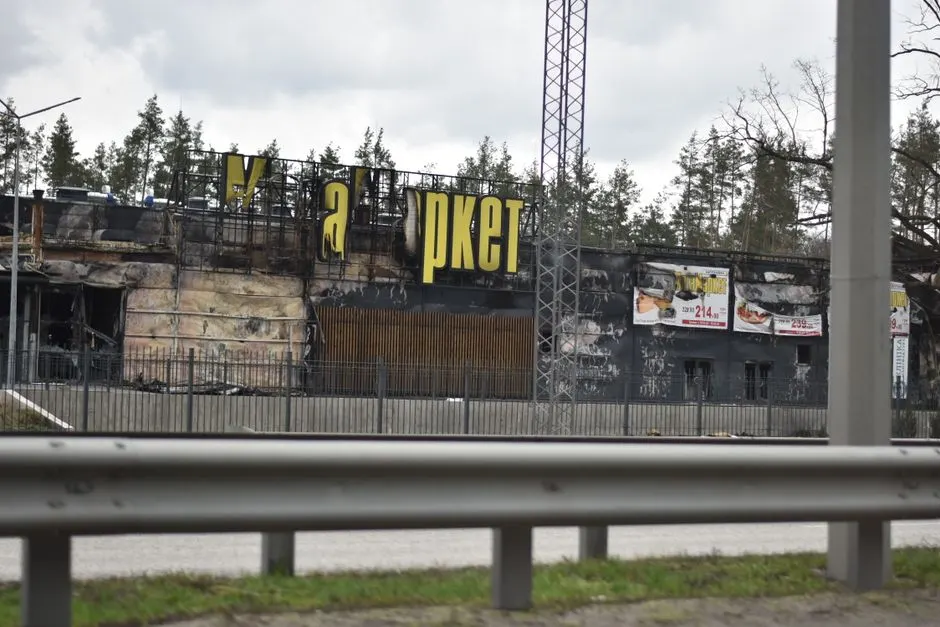
After a commercial fire on Van Nuys Boulevard, the first two things you do are secure the property and call your insurance carrier - in that order. Lock the doors, board the windows, shut off gas and power at the meter if the fire department hasn't already, and open a claim before you touch a single charred shelf. Everything else - cleanup, restoration, reopening - follows from those two moves. This guide walks you through the exact sequence we use with business owners along the Van Nuys Boulevard corridor, from the first hour to the day you unlock the front door again.
Secure the property and call your insurer first
Securing the property and calling your insurer are the two actions that protect every dollar you're about to spend on commercial fire recovery in Pacoima CA. A fire-damaged storefront with a broken window is an open invitation to theft, vandalism, and water intrusion from the next rain. Board up, tarp the roof if it's compromised, and post a no-entry sign. Then call your insurance agent's claims line - not the local office, the 24-hour claims number on your policy.
You need four pieces of information ready for that call: your policy number, the date and approximate time of the fire, the fire department's incident number, and a rough description of the damage. The adjuster will assign a claim number on the spot. Write it down and use it on every document from that moment forward.
If you're in a strip mall or multi-tenant building, also call the landlord. The building owner's policy covers the structure; your policy covers your contents, your build-out, and your business interruption. Those are two separate claims, and mixing them up is the single most common delay we see.
Document everything before cleanup starts
Document the damage before anyone moves a charred box. Insurance adjusters work from evidence, and once soot is wiped or debris is hauled, that evidence is gone. Walk the space with your phone and take wide shots of every room, then close-ups of each damaged item, the electrical panel, the HVAC unit, and the ceiling. Shoot video too - a slow pan of the whole space catches things still photos miss.
Pull together your paper trail in parallel. Gather:
- Purchase receipts or depreciation schedules for equipment, furniture, and inventory
- Lease agreement and any build-out invoices
- Payroll records and two years of profit-and-loss statements for the business interruption claim
- Photos or video of the space from before the fire - phone shots, social media posts, anything showing how it looked
Don't throw anything away yet. Charred shelving, smoke-stained signage, ruined stock - it all stays until the adjuster has seen it or your restoration contractor has photographed and inventoried it. We tell every owner the same thing: the trash pile can wait 48 hours.
How to file a business fire insurance claim in Pacoima CA
Filing a business fire insurance claim in Pacoima CA follows the same path as anywhere else in Los Angeles County, but the documentation bar is higher for commercial losses. Your claim has three parts: structure (the landlord's policy, usually), contents and build-out (your policy), and business interruption (your policy, covering lost income while you're closed).
Submit the claim in writing within the window your policy specifies - most commercial policies require notice within 60 days of the loss, and some require 30. Missing that window is grounds for denial. Attach your photo inventory, a preliminary damage estimate from a licensed contractor, and a written summary of the business interruption you expect.
The adjuster will schedule an inspection, usually within 5 to 10 business days. Be there for it. Walk the space with the adjuster and your restoration contractor at the same time if you can - that's when scope disagreements get settled before they become payment disputes. If the adjuster's estimate comes in low, you have the right to a second opinion from an independent contractor, and we've seen that single step recover $18,000 to $40,000 on mid-size retail losses.
Keep every receipt from day one - board-up materials, temporary security, equipment rental, even mileage to the site. Those are reimbursable under most commercial policies as